Table of Contents
Owning a home is a major financial investment, and protecting it against unexpected damage is essential. Homeowners insurance coverage helps protect your property, personal belongings, homeowners insurance coverage and finances when certain covered events occur. From fires and storms to theft and liability claims, the right policy can provide valuable financial support when problems arise.
However, not every policy covers every type of damage. Understanding what homeowners insurance includes, what it excludes, and which additional protections may be available can help you choose coverage that suits your property and budget.
What Is Homeowners Insurance Coverage?
Homeowners insurance coverage is a type of property insurance that provides financial protection against specific risks involving your home and belongings. It may also offer liability protection if you are legally responsible for another person’s injury or property damage.
A standard homeowners policy typically combines several coverage categories into one package. The exact protection depends on the policy type, coverage limits, exclusions, deductibles, and endorsements you select.
Homeowners should review their policy documents carefully instead of assuming that every possible loss is covered.
What Does Homeowners Insurance Cover?
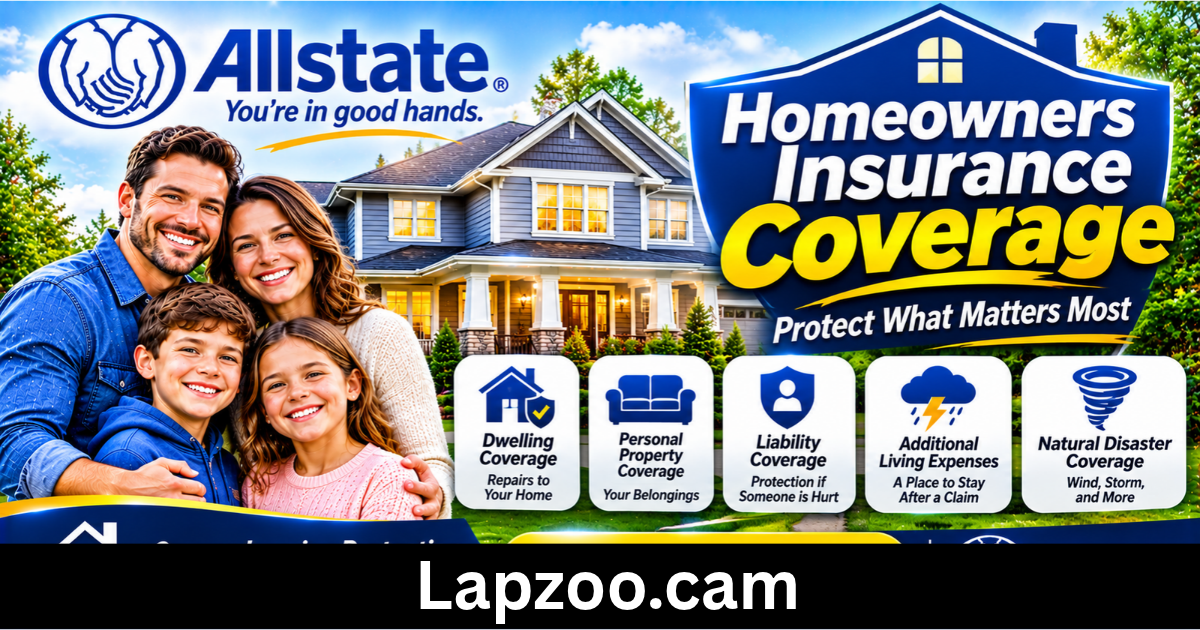
Most standard homeowners insurance policies include several major types of protection.
1. Dwelling Coverage
Dwelling coverage protects the physical structure of your home against covered damage. This may include:
- Roofs and exterior walls
- Floors and ceilings
- Built-in cabinets
- Plumbing and electrical systems
- Attached garages
- Permanently installed fixtures
For example, if a covered fire damages your house, dwelling coverage may help pay for eligible repairs or rebuilding expenses.
The coverage limit should generally reflect the estimated cost of rebuilding your property, not simply its current market value.
2. Other Structures Coverage
Other structures coverage protects qualifying buildings and features that are separate from your main home.
Examples may include:
- Detached garages
- Garden sheds
- Fences
- Gazebos
- Certain standalone workshops
Coverage limits and exclusions vary. If you have expensive detached structures, check whether the standard limit is sufficient.
3. Personal Property Coverage
Personal property coverage helps protect eligible belongings inside or sometimes outside your home when they are damaged or stolen in covered circumstances.
Common examples include furniture, clothing, televisions, computers, kitchen appliances, and other household possessions.
Some valuable belongings, such as jewelry, collectibles, artwork, and expensive electronics, may have special coverage limits. You may need an additional endorsement or separate policy to protect them adequately.
4. Personal Liability Coverage
Personal liability coverage may help protect you financially if you are legally responsible for another person’s injury or property damage.
For example, a visitor might slip on an unsafe walkway and suffer an injury. Depending on the circumstances, your homeowners policy may help cover eligible legal expenses, settlements, or damages up to the policy limit.
This coverage can provide important financial protection beyond the physical structure of your home.
5. Medical Payments to Others
Medical payments coverage can help pay certain minor medical expenses when a guest is accidentally injured on your property, regardless of whether you are legally responsible.
It is generally designed for relatively small medical costs rather than major injury claims. Its limits are usually separate from personal liability coverage.
6. Additional Living Expenses
Additional living expenses coverage, sometimes called loss of use coverage, may help pay extra living costs if a covered event makes your home temporarily uninhabitable.
Depending on the policy, eligible expenses may include:
- Temporary hotel or rental accommodation
- Additional meal costs
- Certain temporary living expenses
- Other reasonable costs caused by displacement
Coverage is subject to policy limits, conditions, and the time required to repair the property.
What Perils Are Covered by Homeowners Insurance?
The risks covered depend on your policy form. Many standard homeowners policies provide protection against events such as:
- Fire and smoke damage
- Lightning strikes
- Windstorms and hail
- Certain explosions
- Theft and vandalism
- Damage caused by the weight of snow or ice
- Certain accidental water damage
- Falling objects
Some policies cover personal property against a specific list of named perils, while others provide broader open-peril protection subject to exclusions.
For example, an HO-3 policy commonly provides open-peril coverage for the dwelling and named-peril coverage for personal property. The actual policy wording determines what is covered.
What Does Homeowners Insurance Usually Not Cover?
Understanding exclusions is just as important as understanding coverage. Standard homeowners insurance generally does not cover every type of property loss.
Flood Damage
Damage caused by flooding is generally excluded from standard homeowners insurance. Homeowners who need flood protection may have to purchase separate flood insurance.
Earthquake Damage
Earthquake damage is generally excluded from standard policies. Separate earthquake coverage or an endorsement may be available in some locations.
Normal Wear and Tear
Insurance is designed for covered unexpected losses, not routine maintenance. Gradual deterioration, aging materials, and ordinary wear and tear are generally not covered.
Neglected Maintenance
Damage caused by poor maintenance or long-term neglect may be excluded. For example, a gradual plumbing leak that goes unrepaired may not qualify for coverage.
Pest and Animal Damage
Damage caused by termites, rodents, and certain other pests is generally excluded.
Sewer or Drain Backup
Water damage caused by backed-up drains or sump pump failures may require an additional endorsement, depending on the policy.
Always review the exclusions section and ask your insurer about risks that are especially relevant to your location.
Types of Homeowners Insurance Policies
Different homeowners insurance policy forms provide different levels of protection.
| Policy type | General purpose |
|---|---|
| HO-1 | Basic named-peril coverage; limited availability |
| HO-2 | Broader named-peril protection |
| HO-3 | Common homeowners policy with broad dwelling protection |
| HO-4 | Renters insurance for tenants’ belongings and liability |
| HO-5 | Broader protection for eligible homes and personal property |
| HO-6 | Coverage designed for condominium owners |
| HO-8 | Modified coverage for certain older homes |
Not every policy type is available from every insurer. The best option depends on whether you own a house, rent an apartment, or own a condominium.
How Much Homeowners Insurance Coverage Do You Need?
Choosing the right coverage limits is essential. Too little insurance may leave you responsible for substantial rebuilding expenses, while unnecessary coverage can increase your premium.
Consider these important factors:
Estimate Your Home’s Rebuilding Cost
Calculate how much it would cost to reconstruct your home using comparable materials and labor. Local construction prices, property size, and special features can affect this estimate.
Calculate Your Personal Belongings
Create a home inventory listing furniture, electronics, clothing, appliances, and valuable possessions. Photos, receipts, and purchase records can help document ownership.
Review Liability Limits
Consider your financial situation and potential liability risks when choosing personal liability coverage. An insurer or licensed agent can explain available limits and whether additional protection is appropriate.
Consider Special Risks
If your property is exposed to floods, earthquakes, hurricanes, or other regional hazards, investigate whether separate coverage or endorsements are necessary.
How to Choose the Right Homeowners Insurance Coverage
Before purchasing a policy, compare several insurers and examine more than just the quoted premium.
- Compare coverage limits: Check dwelling, personal property, and liability protection.
- Review deductibles: Understand how much you must pay before insurance contributes to a covered claim.
- Check exclusions: Identify risks that are not included in the policy.
- Ask about endorsements: Explore additional protection for valuable possessions or specific risks.
- Research the insurer: Review customer service, claims handling, and financial strength.
- Update coverage regularly: Reassess your policy after renovations or major purchases.
A policy that matches your property’s risks and rebuilding needs can provide better protection than one selected only because it has the lowest price.
Frequently Asked Questions
1. What is included in homeowners insurance coverage?
A standard homeowners policy commonly includes dwelling coverage, other structures coverage, personal property protection, personal liability, medical payments to others, and additional living expenses.
2. Does homeowners insurance cover water damage?
It may cover certain sudden and accidental water damage, such as damage from a covered plumbing failure. Flooding, gradual leaks, and neglected maintenance are generally excluded unless additional coverage or specific policy terms apply.
3. Does homeowners insurance cover roof damage?
Roof damage caused by covered events, such as certain windstorms or hail, may be covered. Normal aging, deterioration, and maintenance problems are generally not covered.
4. Does homeowners insurance cover stolen belongings?
Most standard policies provide personal property protection against covered theft. However, special limits may apply to jewelry, cash, collectibles, and other valuable items.
5. Is homeowners insurance required by law?
There is generally no federal law requiring homeowners to purchase insurance. However, mortgage lenders commonly require borrowers to maintain adequate coverage while a mortgage is active.
6. What is the difference between replacement cost and actual cash value?
Replacement cost coverage generally pays the eligible cost of replacing damaged property without deducting depreciation, subject to policy terms. Actual cash value accounts for depreciation and may result in a smaller payment.
7. Can I add more coverage to my homeowners policy?
Yes. Depending on your insurer and location, you may be able to add endorsements for valuable belongings, water backup, identity theft assistance, or other specific risks.
Conclusion
Homeowners insurance coverage plays an important role in protecting your house, belongings, and financial security. Standard policies generally include dwelling protection, personal property coverage, liability protection, and additional living expenses, but exclusions and limits can vary considerably. homeowners insurance coverage Before choosing a policy, review the covered risks, deductibles, rebuilding estimates, and optional endorsements. Comparing providers and understanding the policy details can help you select protection that fits your home and gives you greater financial confidence.